T12 in real estate: what a trailing 12-month statement shows and how to read it
For CRE lenders, analysts and investors: what a T12 operating statement contains, a worked multifamily example, how to normalize it, and how to stop spreading T12s by hand.
Key takeaways
- Trailing 12 months (TTM) means the most recent 12 months, whatever the fiscal year. In real estate, a T12 is the property's operating statement for those months, month by month, with a 12-month total.
- Lenders and buyers use it to find the property's actual net operating income (NOI), which drives value and the debt service coverage ratio (DSCR).
- NOI = effective gross income minus operating expenses. Debt service, depreciation and capital expenditures sit below the NOI line.
- A T12 should be read with the rent roll: the T12 shows what the property earned, the rent roll shows what it's set up to earn now.
- Analysts normalize a T12 before using it: removing one-off items, adding missing expenses such as a management fee or reserves, and checking monthly trends.
On this page
Trailing 12 months (TTM, or T12) means the most recent 12 consecutive months, whatever the fiscal year. In real estate, a T12 is a property's operating statement for those months: rent and other income, vacancy and operating expenses for each month, and the net operating income (NOI) they add up to. Lenders, buyers and appraisers read it with the rent roll to see what a property actually earns.
What is a T12 in real estate?#
Outside real estate, trailing twelve months (TTM, or LTM for "last twelve months") is a general finance term: a company's TTM revenue is its revenue for the last 12 months. In commercial real estate, "T12" nearly always means the T12 operating statement, or T12 report: the property's profit and loss for those months, usually exported from the property manager's accounting system.
It has one column per month, a total column and a row for every income and expense account. The owner's financing costs, depreciation and capital projects stay out of NOI, because they don't show how the property itself performs.
What's on a T12 operating statement#
| Section | Typical line items |
|---|---|
| Gross potential rent (GPR) | Rent if every unit were leased at market or scheduled rent |
| Rent adjustments | Vacancy loss, loss to lease, concessions, bad debt, non-revenue units (model, office, employee units) |
| Other income | Parking, laundry, pet fees, application fees, utility reimbursements (RUBS), storage |
| Effective gross income (EGI) | GPR less adjustments plus other income |
| Operating expenses | Payroll, repairs and maintenance, turnover, utilities, management fee, insurance, real estate taxes, marketing, administrative, contract services |
| Net operating income (NOI) | EGI minus operating expenses |
Some T12s also show replacement reserves, capital expenditures and debt service below NOI. Analysts separate those out.
A worked T12 example#
A 100-unit multifamily property with an average scheduled rent of $1,500 a month:
| Line | 12-month total |
|---|---|
| Gross potential rent (100 × $1,500 × 12) | $1,800,000 |
| Vacancy loss (6%) | −$108,000 |
| Concessions | −$18,000 |
| Bad debt | −$9,000 |
| Other income | $60,000 |
| Effective gross income | $1,725,000 |
| Payroll | $190,000 |
| Repairs and maintenance | $95,000 |
| Utilities | $120,000 |
| Management fee (4% of EGI) | $69,000 |
| Insurance | $75,000 |
| Real estate taxes | $210,000 |
| Administrative and marketing | $36,000 |
| Total operating expenses | $795,000 |
| Net operating income | $930,000 |
If the loan's annual debt service is $700,000, the DSCR is $930,000 ÷ $700,000 = 1.33x. Lenders often deduct replacement reserves too: Fannie Mae's multifamily guide uses at least $200 per unit a year, or $20,000 here, which leaves net cash flow of $910,000 and a DSCR of 1.30x.
At a 6% cap rate, the same NOI implies a value of about $15.5 million ($930,000 ÷ 0.06), so a small change in NOI moves both value and loan size.
Why lenders and investors use the T12#
It's actual performance
Unlike a pro forma, it shows what the property collected and spent.It covers a full year
Twelve months catch seasonal vacancy, heating and cooling costs, and annual bills such as insurance and taxes.It shows trends
Monthly columns reveal rising vacancy, growing concessions or expense spikes that an annual total hides.It feeds the key ratios
NOI drives DSCR, debt yield (NOI ÷ loan amount) and value (NOI ÷ cap rate).
T12s are used in CRE underwriting, acquisition due diligence, appraisals, loan servicing and annual reviews, for multifamily, office, retail, industrial, self-storage and hospitality properties.
How to read and normalize a T12#
A T12 straight from the property manager is rarely ready to underwrite. Analysts adjust it in six steps:
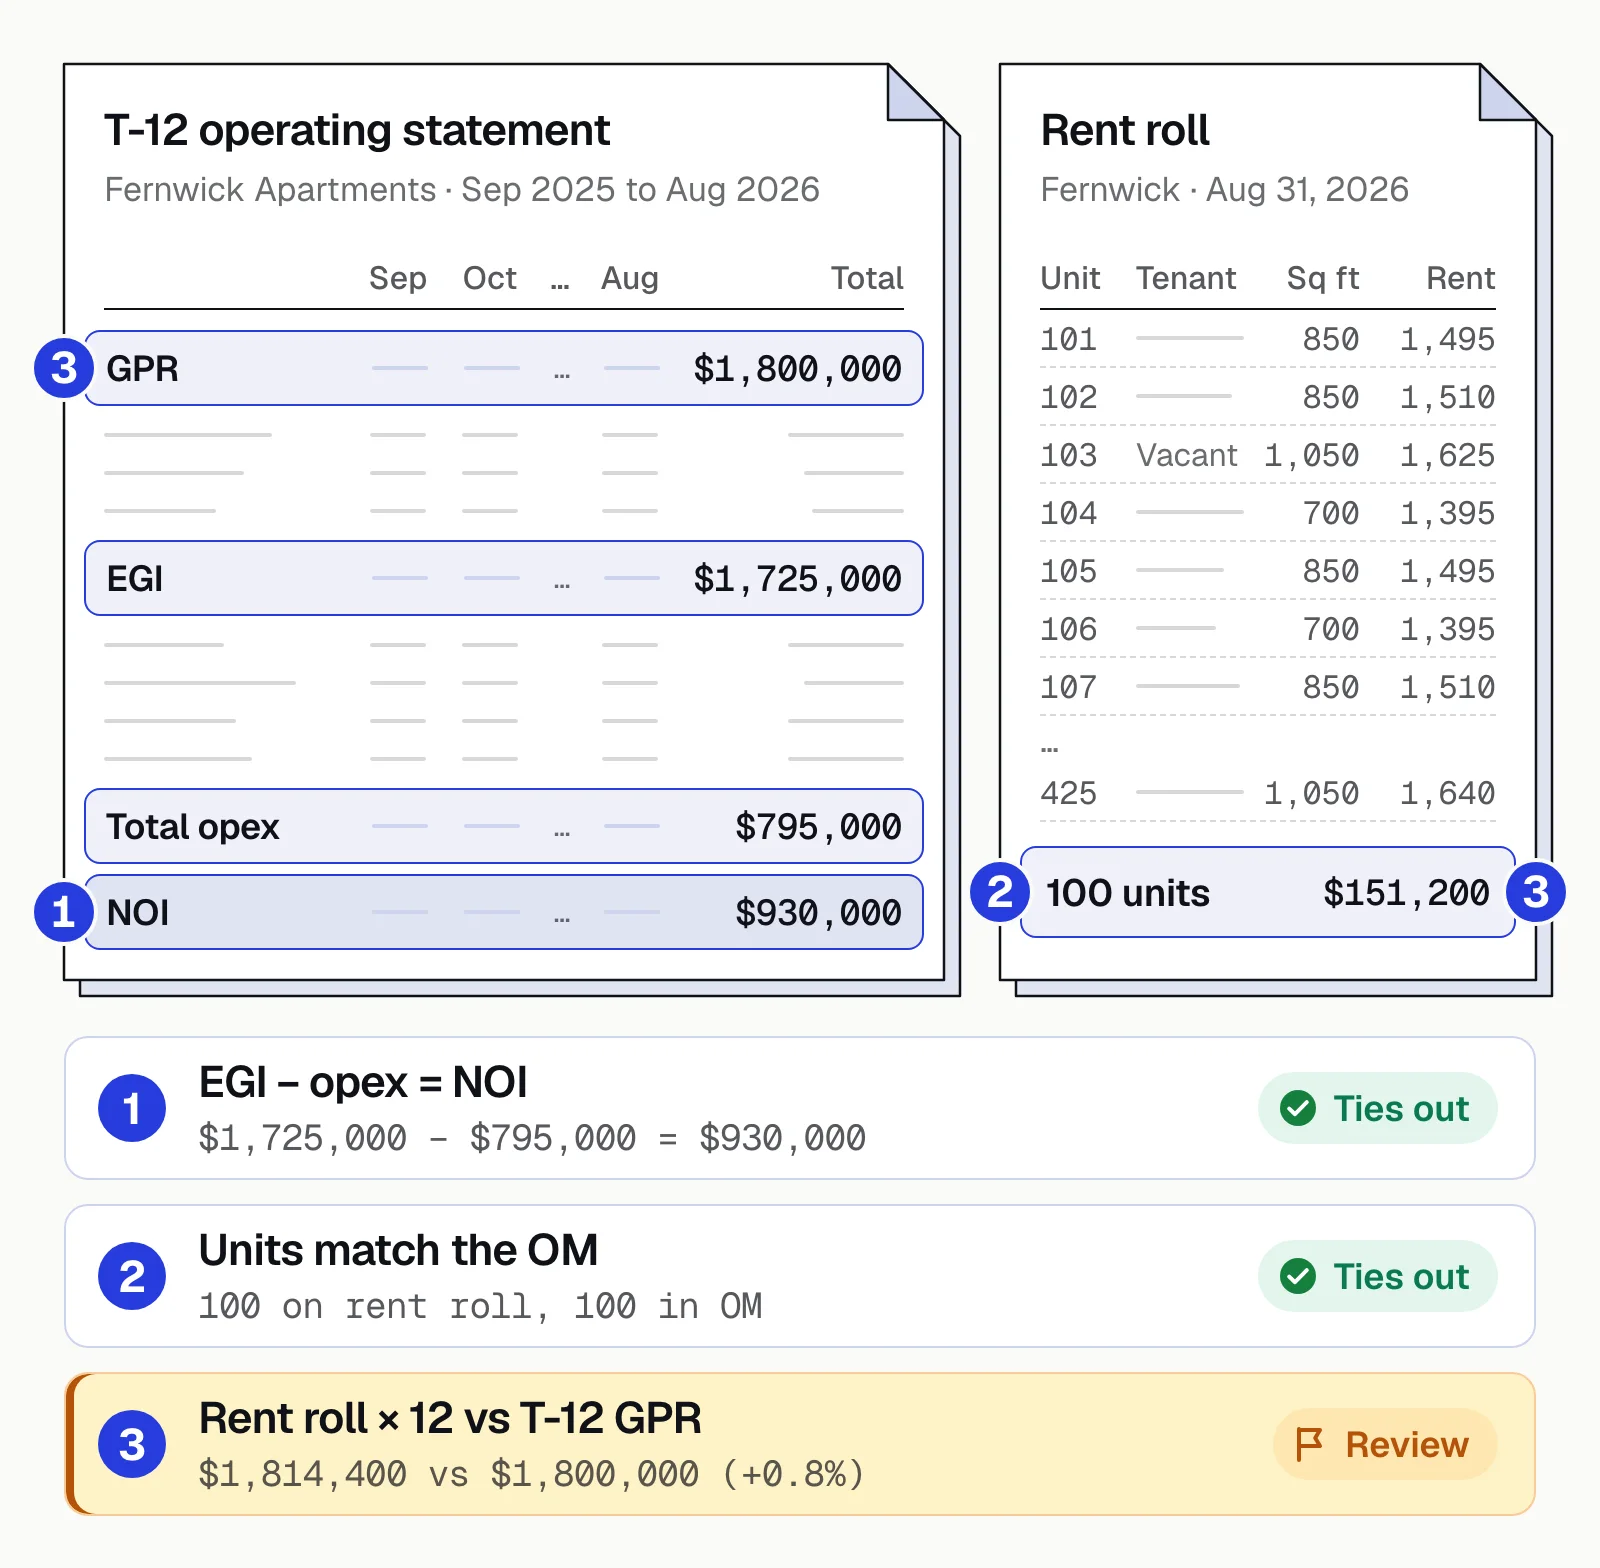
- Tie it to the rent rollCompare recent rental income with the rent roll's in-place rent. A big gap needs an explanation.
- Remove one-off itemsA one-time insurance refund, a tax appeal settlement, or a large repair that was really a capital project.
- Add what's missingA management fee if the owner self-manages (Fannie Mae generally uses at least 3% of effective gross income), replacement reserves, and taxes reassessed at the purchase price.
- Check the trendIf the last 3 months differ from the 12-month average, look at the T3 annualized (last 3 months × 4) too.
- Compare to benchmarksExpenses per unit or per square foot against similar properties show lines that look too low.
- Map it to your chart of accountsEvery property manager names accounts differently. A standard template is what lets you compare deals.
For the rent roll side, see rent roll analysis.
T12 vs rent roll vs pro forma#
| T12 | Rent roll | Pro forma | |
|---|---|---|---|
| What it shows | Last 12 months of income and expenses | Today's units or tenants, rents and leases | Projected income and expenses |
| Time frame | Historical | Point in time | Future |
| Used for | Actual NOI, trends, DSCR | Current income, occupancy, lease expirations | Business plan, upside |
| Reliability | High, if tied to bank records | High, if tied to leases | Assumption-driven |
To tie the first two together, take rent in place plus market rent for vacant units, times 12, and compare it with the T12's gross potential rent. Here's the same 100-unit property:
Automating T12 spreading#
Spreading a T12 by hand means retyping 12 columns and dozens of rows into your model and mapping every account, in a different layout for each property manager. A portfolio loan can bring dozens of them.
- Property manager PDFs
- Scanned statements
- Portfolio loan packages
- 01Extract every month and line
- 02Check that totals foot
- 03Map to your chart of accounts
- 04Send exceptions to review
Docsumo is an intelligent document processing (IDP) platform. It reads T12s, rent rolls and other financial statements in any layout, scans included, and joins tables that run across pages. Fields it's unsure about go to your reviewer with the source line highlighted. Checks and mappings for your template, such as footing the totals or mapping accounts to your chart, are workflow steps you set up (an AI step or your own Python code). Data reaches your model through the API and webhooks, or downloads to Excel. It doesn't make the normalization calls or underwrite the loan: those stay with your analysts. More in commercial real estate data extraction.
The bottom line#
A T12 is the property's last 12 months of income and expenses, and it's where NOI, DSCR and value start. Read it month by month, tie it to the rent roll, normalize it for one-offs and missing expenses, and map it to a standard template. Automating the extraction and mapping leaves analysts the judgment calls instead of the typing.
Book a demo with a few of your own T12s and rent rolls, or start a free trial.
Frequently asked questions#
What does T12 mean in real estate?
T12 stands for trailing 12 months. In real estate it's the property's operating statement for the most recent 12 months, showing rent and other income, vacancy and operating expenses month by month, and the resulting net operating income.
Is a T12 the same as a P&L?
Close to it. A T12 is the property's profit and loss for the last 12 months, usually with a column for each month, but it's built to show net operating income, so debt service, depreciation and capital projects either sit below NOI or are left off.
What is the difference between a T12 and a rent roll?
A T12 is historical income and expenses over 12 months. A rent roll is a snapshot of every unit or tenant today, with rent, lease dates and deposits. Analysts compare them to check that collected rent matches the leases in place.
What is the difference between T12 and pro forma?
A T12 shows what the property actually did. A pro forma projects what it could do, usually with higher rents or lower expenses. Lenders underwrite mainly from the T12 and treat pro forma assumptions with caution.
What is a T3 annualized?
It's the last three months of income multiplied by four. Analysts use it when recent months differ from the 12-month average, for example after a lease-up or rent increases. Fannie Mae's multifamily guide, for one, looks at trailing 3-month rent collections, annualized, when it sets net rental income.
How is TTM calculated for a company?
Take the latest fiscal year figure, add the current year-to-date figure and subtract the prior year's same year-to-date period. For example, $240 million for the last fiscal year plus $130 million this half-year minus $115 million last half-year gives $255 million TTM.